Quantum Advisors Private Limited (QAPL) is incorporated in India and is registered with the Securities and Exchange Board of India (SEBI) as Portfolio Manager vide registration number INP000000187.
India Equities: 4 Catalysts for Potential Outperformance
We identify potential catalysts which could help reverse India’s relative underperformance
Slower GDP growth and earnings growth, a depreciating Indian currency due to capital outflows, and limited participation in the AI thematic seems to have combined over the past 2 years to deliver a record underperformance for Indian Equities and continued large outflows by foreign investors.
Chart 1: India’s record underperformance against EM
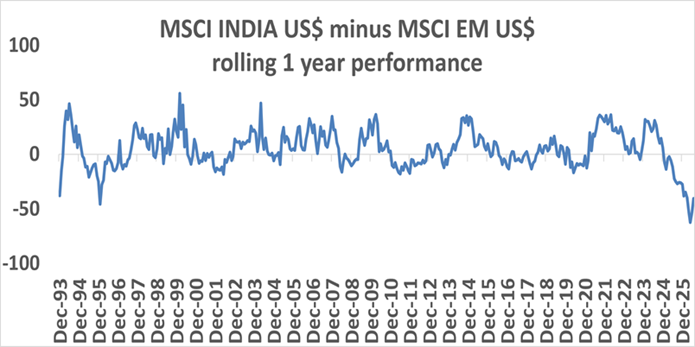
Source: Refinitiv DataStream, Data till August 2026; Chart depicts % Year-On-Year relative performance. MSCI Indices are price returns in Gross USD, EM = Emerging Markets
This is only for representation and understanding purpose and does not assure any promise or guarantee that the historical results is indicative of future results.
The relative underperformance of India was driven more by the strong performance of companies in the technology, semiconductors, memory storage sectors which are well represented in countries like Korea and Taiwan.
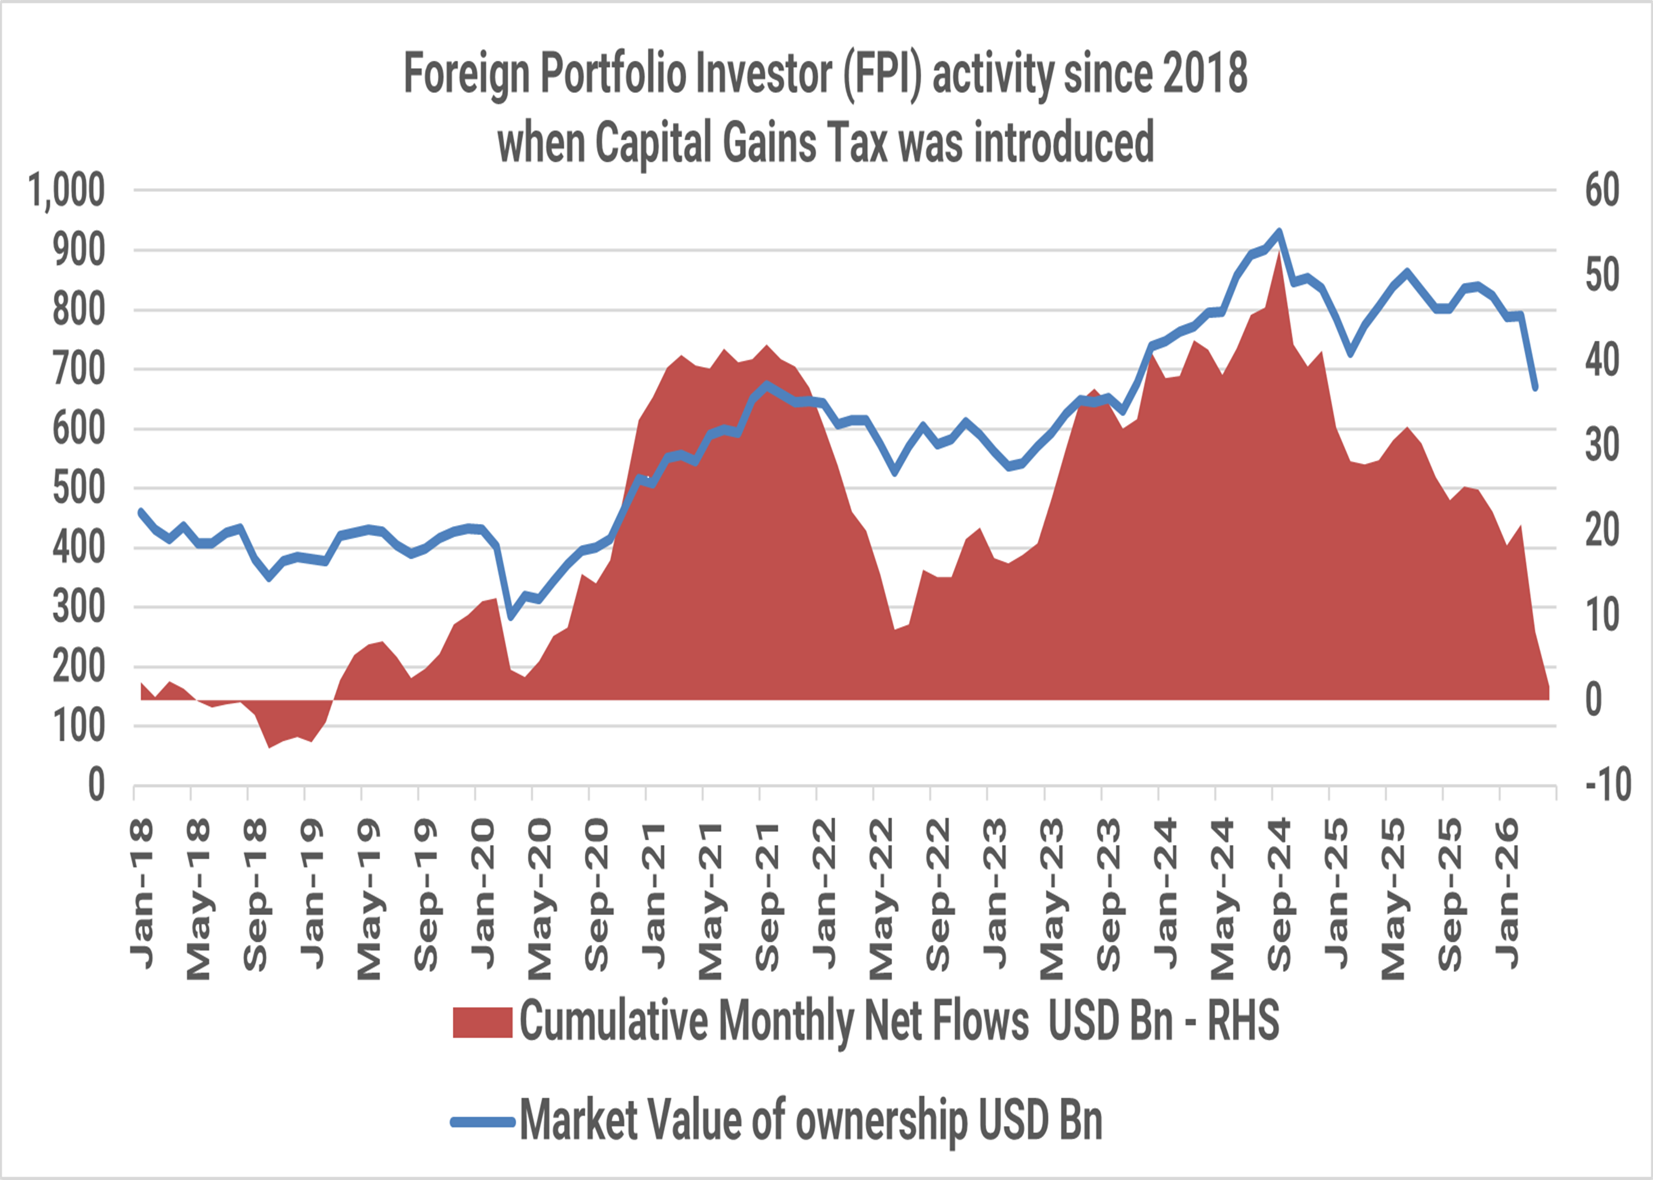
India’s underperformance was also driven by continued foreign portfolio outflows. The extent of recent outflows has meant that cumulative foreign portfolio inflows into equities is now negative over 8 years. We start this data series from 2018 as that was the year when capital gains tax on equities was re-introduced.
Chart 2: Foreign Investors are ‘Exit’ing India?
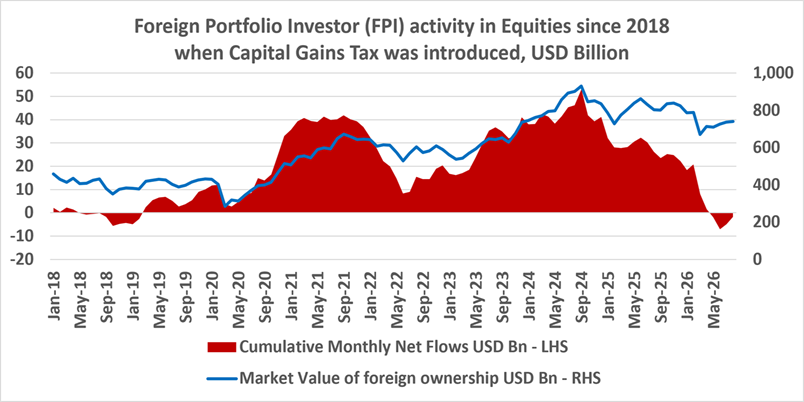
Source for Chart: NSDL FPI Monitor, SEBI, Calendar Year Data till August 2026
Since September 2024, which happened to be India’s stock market peak, FPIs have sold over USD 50bn which impacted not only the market performance but also contributed to the poor performance of the Indian currency in 2025/26. Despite the selling, FPIs still own ~USD 800 bn worth of Indian stocks. However, they remain under-allocated, and the extent of under-allocation has increased.
What will reverse this trend of under-performance, outflows and under-allocation? We wrote in our 2026 outlook (Complicated 2025, Simpler 2026?) that India needs to get back to its long-term simple story of consistent real and nominal GDP growth which has been reflected in market returns.
We identify 4 potential catalysts which could combine to make Indian equities attractive and bring it back into global investors allocation decisions.
Catalyst 1: India as a diversifier to global AI risks
AI as a thematic investment has been remarkably successful in investment portfolios. We wrote about it in August 2026 to show the dominance of AI in investment portfolios and market performance.
However, there seems to be rising concentration in equity indices driven by stocks linked to the AI thematic.
Also, the exposure to the AI thematic is not only in public markets. As the profile chart shows and as we learn from other reports, there is likely to be increased exposure to AI through ownership of bonds issued by hyperscalers, exposure in private markets, and through investments in datacentres and its ecosystem from the infrastructure and real estate portfolios. There is the risk of some of these allocations being correlated and thus increasing the risk profile.
Chart 3 and 4: AI concentration risk in global portfolio allocations is rising.
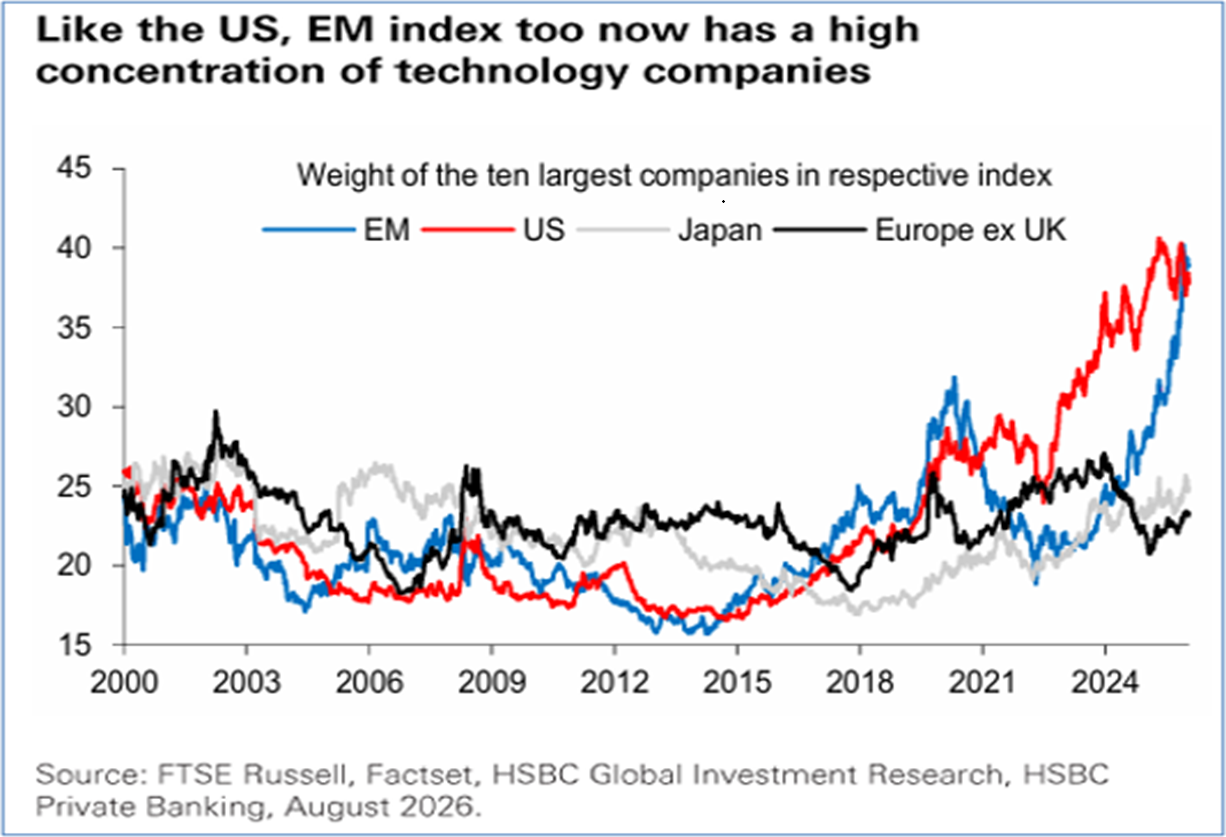
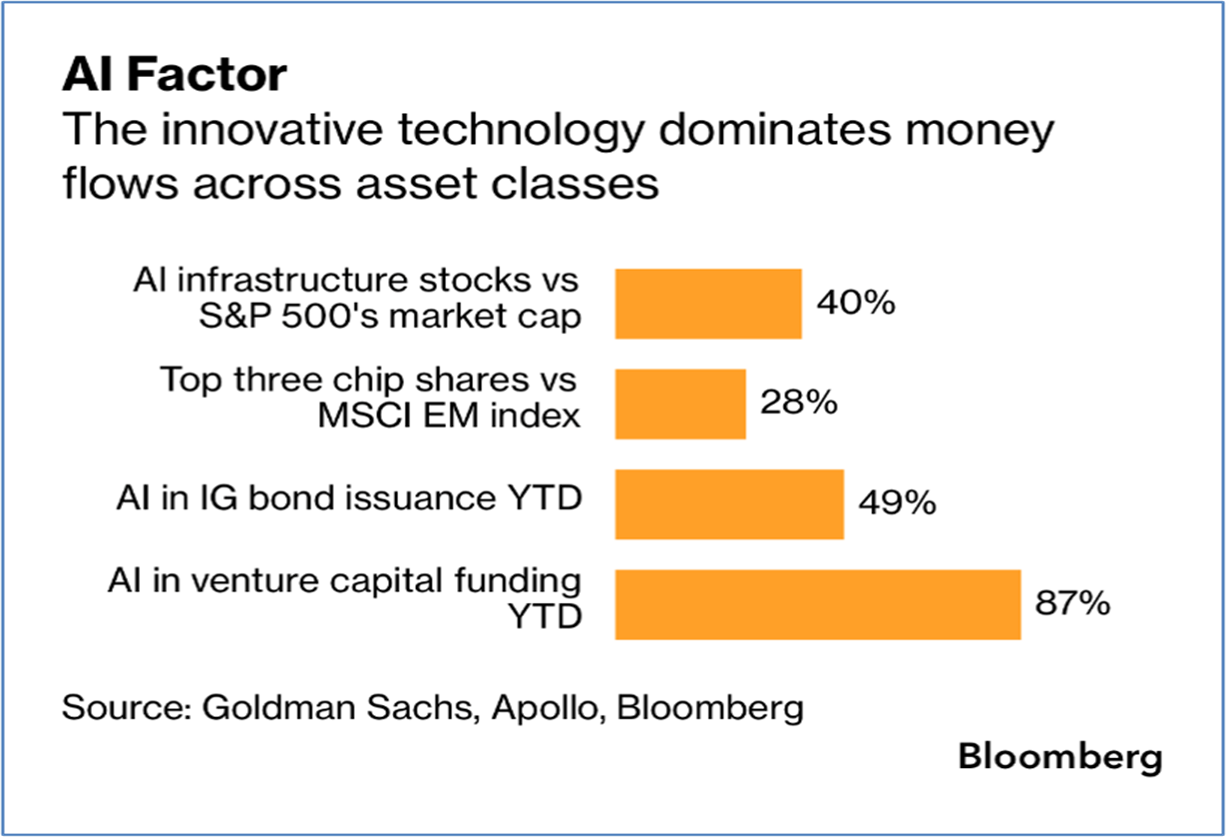
Source for Chart 3: HSBC Investment Research, CIO Academy; Chart represents the weight of the Top 10 stocks in the respective FTSE Russell index used. The report states that the increase in concentration in these indices is driven by technology companies. There is no assurance or indication that the above composition of the index will be sustained in future and the same may vary as per the market conditions, from time to time. Source for Chart 4: Sourced from Bloomberg article - AI boom is making diversifying investment tougher for wall street; September 20, 2026
India seems to have missed out on most of these AI related exposures and its performance as evidenced by the relative and absolute market returns over the last 18-24 months.
Table 1: India’s record underperformance – Has it reversed?
| (Gross Absolute Total Returns in USD) | 1 Month | YTD | Sept 2024 to July 2026 (Annualised Returns in Bracket) |
|---|---|---|---|
| MSCI India Index | 1.8% | -8.1% | -12.5% / (-7.0%) |
| MSCI Korea Index | -17.1% | 81.5% | 185.9% / (77.4%) |
| MSCI Taiwan Index | -5.3% | 54.0% | 126.1% / (56.1%) |
| MSCI Emerging Markets Index | -3.0% | 20.3% | 58.9% / (28.8%) |
Source: Bloomberg, MSCI, as of July 31, 2026. Indian markets peaked in September 2024 and hence we have used that as a representative period to show cumulative performance since then. Past performance may or may not sustain in the future. Returns may increase or decrease as a result of currency fluctuations.
However, as global institutional investors start thinking about AI as a risk allocation, we believe they should look at Indian public equities as an ‘AI’ risk diversifier.
Catalyst 2: India’s under-allocation in global portfolios
India’s weight in global GDP stood at 3.3% as of 2025. India’s weight in global market capitalization declined from ~4% to below ~3.3%. India’s weight in MSCI All Country World Index (ACWI) fell to 1.4%. and India’s weight in global emerging market index fell by 40% from ~21% to ~11%
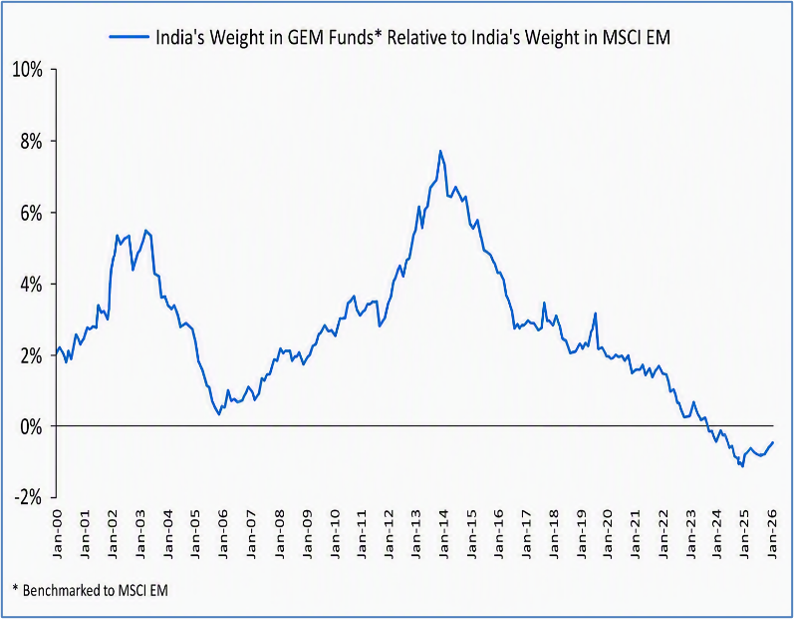
Chart 5 and 6: India is losing weight in global indices and GEM portfolios
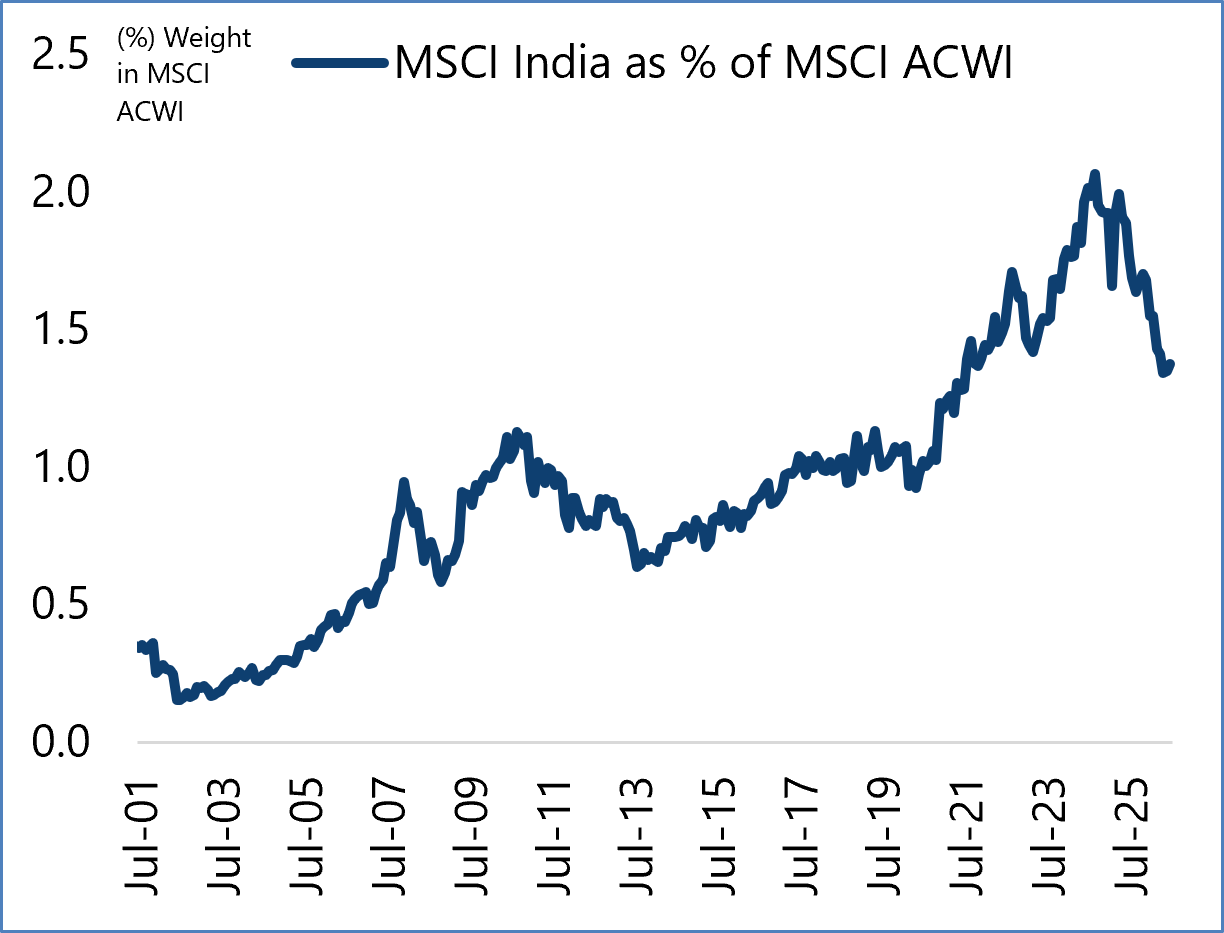
Source: Jefferies Research, August 2026
Source: Morgan Stanley Research, August 2026
‘ACWI’ = All country world index. ‘GEM’ = global emerging market Right chart considers Global Emerging Market (GEM) Funds which use the MSCI EM as its benchmark. It calculates these funds India weight in their portfolio in relation to India’s weight in the index to calculate the under/overweight of India in their portfolio Past performance does not guarantee future return. The graph is only for representation and understanding purpose and does not assure any promise or guarantee that the historical results is indicative of future results. The graph is only for representation and understanding purpose and does not assure any promise or guarantee that the historical results is indicative of future results.
Not only has India lost weight in global indices, but India is also ‘under-weight’ in global emerging market (EM) portfolios. India has historically traded at a premium to global and emerging market valuations and has remained an over-weight in portfolios. This bring us to our next potential catalyst for India’s outperformance
Catalyst 3: India’s relative valuations are now attractive and should draw potential flows
The reason India trades at a premium is because historically Indian companies on an average have had a higher earnings growth and a better return on equity profile as compared to emerging market or world indices
That of course faded away in the past 2 years which explains India’s relative underperformance. However, if the impact of AI theme on global investment and earnings cycle reduces and if India gets back to its higher financial return profile, we believe the historical gap may get restored.
This could also mean that India then could trade at its long-term average valuations with respect to emerging markets or world indices.
Chart 7 and 8: India commands premium valuations on better financial return profile
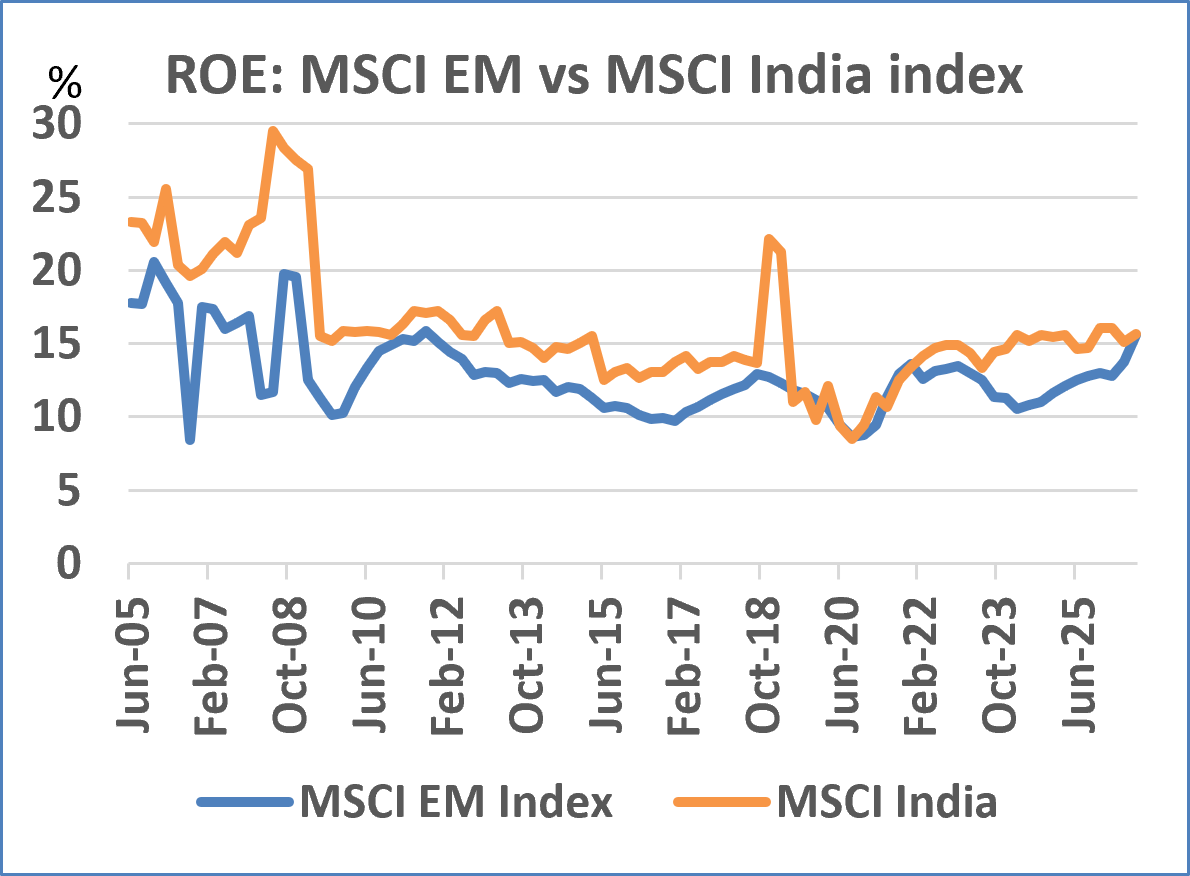
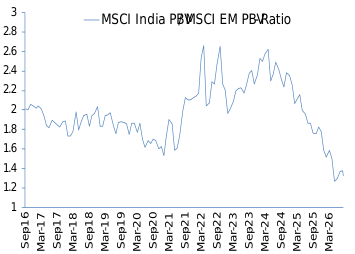
Source: Bloomberg | ROE data as of June 2026; ROE – Return on Equity;
Chart 8 shows MSCI India as a ratio over MSCI emerging market index for PBV: price to book value ratio This is only for representation and understanding purpose and does not assure any promise or guarantee that the historical results is indicative of future results.
Given that India has lost weight in global indices, global portfolio managers are under-weight India in their portfolio and that India’s relative valuation is much more palatable now than before, we believe that a positive sentiment towards India can draw in significant inflows.
As you can see in chart 2 above, foreign inflows into India could increase materially in a short period of time. India received upwards of USD 40 billion between 2020 and 2021 and again between 2023 and 2024.
As of now external conditions remain stressed for India, especially with the West Asia conflict driving up prices of oil, gas and fertilizers. However, as we wrote in our outlook piece, we believe there could be a steady investment and consumption recovery in India.
Catalyst 4: India’s GDP, investment and earnings recovery
Corporate revenue and capex remains on a steady uptrend supported by improvement in income growth and facilitated by an increase in industrial credit growth. We would expect nominal GDP to trend in double digits while consensus estimates on corporate earnings remain in double digits for the current and coming financial year.
India large-cap equity valuation and positioning seems attractive
We believe that Indian large-cap companies are attractively valued, have good balance sheets and are well placed to participate in the economic recovery.
Chart 9: India large-cap trades at long-term average valuations
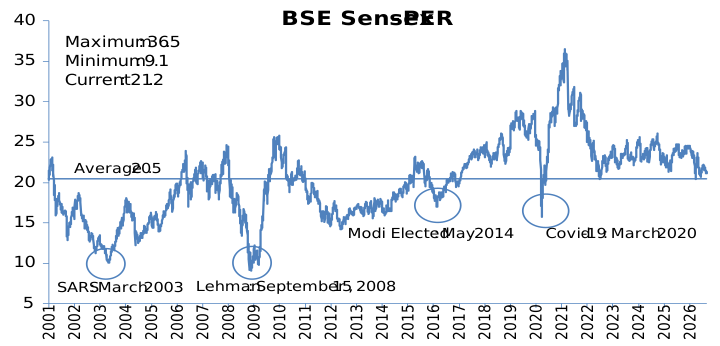
Source: Bloomberg | PER = Price to Earnings Ratio; BSE-30 Sensex Index
Past performance does not guarantee and is not indicative of future results
The table below also provides some historical context of past periods of flat to negative returns and the prospective returns 3 and 5 years ahead.
Table 2: Large Cap equities poised for a rebound
| Start Date | End Date | Window Return in INR Absolute Returns |
Next 3 Yrs in INR Absolute Returns |
Next 5 Yrs in INR Absolute Returns |
Avg US 10 Yr G-Sec Yield for Window Period |
|---|---|---|---|---|---|
| 29-06-2007 | 30-06-2009 | 1.4% | 27.5% | 88.2% | 3.7% |
| 30-09-2009 | 30-09-2011 | -0.6% | 67.2% | 85.1% | 3.2% |
| 30-11-2009 | 30-11-2011 | -1.9% | 84.4% | 81.0% | 3.0% |
| 30-04-2010 | 30-04-2012 | 1.7% | 61.9% | 88.7% | 2.7% |
| 31-05-2010 | 31-05-2012 | -0.9% | 77.5% | 107.5% | 2.6% |
| 30-06-2010 | 29-06-2012 | 1.7% | 64.2% | 91.5% | 2.6% |
| 30-07-2010 | 31-07-2012 | -0.2% | 69.1% | 104.8% | 2.5% |
| 31-08-2010 | 31-08-2012 | -0.2% | 56.9% | 100.4% | 2.5% |
| 31-12-2010 | 31-12-2012 | -1.4% | 39.3% | 89.4% | 2.3% |
| 31-03-2011 | 01-04-2013 | 0.2% | 42.6% | 100.5% | 2.1% |
| 01-12-2014 | 30-11-2016 | -1.5% | 52.5% | 119.7% | 2.0% |
| 31-12-2014 | 30-12-2016 | 1.2% | 54.7% | 125.6% | 2.0% |
| 30-01-2015 | 31-01-2017 | -0.4% | 45.4% | 115.6% | 2.0% |
| 29-06-2018 | 30-06-2020 | -1.5% | 93.2% | 163.1% | 2.1% |
| 31-07-2018 | 31-07-2020 | -0.2% | 84.8% | 137.5% | 2.0% |
| 31-08-2018 | 31-08-2020 | -0.2% | 75.3% | 127.9% | 1.9% |
| 31-08-2024 | 31-08-2026 | -2.4% | ? | ? | 4.3% |
Source: Bloomberg, calculated for Nifty-50 Index, all returns mentioned are in absolute terms and are not annualized. The above table is only for information and representation purpose only. Past performance is not a guarantee and is not indicative of future results.
Important Disclosures & Disclaimers
Quantum Advisors Private Limited (QAPL) is registered in India and holds a Portfolio Management License from Securities and Exchange Board of India (SEBI), India vide registration number INP000000187. It is also registered with the Securities Exchange Commission, USA as an Investment Adviser and a Restricted Portfolio Manager with the Canadian Provinces of British Columbia (BCSC), Ontario (OSC), and Quebec (AMF). It is not registered with any other regulator. (Note- Registration with the above regulators does not imply any level of skill or training).
Investments in markets is subject to Market Risk. There is no guarantee or assurance that the historical results are indicative of future results.
The views expressed herein shall constitute only the opinions and any information contained in this material shall not be deemed to constitute an advice or an offer to sell/purchase or as an invitation or solicitation to invest in any security and further Quantum Advisors Private Limited (QAPL) and its employees/directors shall not be liable for any direct or indirect loss, damage, liability whatsoever arising from the use of this information.
The views expressed in the article are opinion formed basis internal research and data sourced from third party. Information sourced from third parties cannot be guaranteed or was not independently verified. Whilst no action has been solicited based upon the information provided herein, due care has been taken to ensure that the facts are accurate, and the views given are fair and reasonable as on date. All the forward-looking statements made in this communication are inherently uncertain and we cannot assure the reader that the results or developments anticipated will be realized or even if realized, will have the expected consequences to or effects on, us or our business prospects, financial condition or results of operations.
Readers are cautioned not to place undue reliance on these forward-looking statements in making any investment decision. Forward-looking statements made in this communication apply only as of the date of this communication. While we may elect to update forward-looking statements from time to time, we specifically disclaim any obligation to do so, even if internal estimates change, unless otherwise required by applicable Securities laws.
This article is for educational and discussion purposes only and is not intended as an offer or solicitation for the purchase or sale of any investment in any jurisdiction. No advice is being offered nor recommendation given.
Recipients should exercise due care and caution and if necessary, obtain the professional advice prior to taking any decision based on this information.
The stocks/securities discussed in this article have been featured purely for illustration and information purpose only. This is not a recommendation to buy or sell in these stocks or sectors.
The "Index" is a product of Asia Index Private Limited (AIPL), which is a wholly owned subsidiary BSE has been licensed for use by QAPL. BSE® is a registered trademark of BSE Limited (“BSE”), and these trademarks have been licensed for use by AIPL and sublicensed for certain purpose by QAPL. All rights reserved. Redistribution, reproduction and/or photocopying in whole or in part are prohibited without written permission of AIPL. For more information on any of AIPL’s indices please visit http://www.asiaindex.com/. None of AIPL, BSE, their affiliates nor their third party licensors make any representation or warranty, express or implied, as to the ability of any index to accurately represent the asset class or market sector that it purports to represent and none of AIPL, BSE or their affiliates nor their third party licensors shall have any liability for any errors, omissions, or interruptions of any index or the data included therein.
Certain information contained herein (the “Information”) is sourced from/copyright of MSCI Inc., MSCI ESG Research LLC, or their affiliates (“MSCI”), or information providers (together the “MSCI Parties”) and may have been used to calculate scores, signals, or other indicators. The Information is for internal use only and may not be reproduced or disseminated in whole or part without prior written permission. The Information may not be used for, nor does it constitute, an offer to buy or sell, or a promotion or recommendation of, any security, financial instrument or product, trading strategy, or index, nor should it be taken as an indication or guarantee of any future performance. Some funds may be based on or linked to MSCI indexes, and MSCI may be compensated based on the fund’s assets under management or other measures. MSCI has established an information barrier between index research and certain Information. None of the Information in and of itself can be used to determine which securities to buy or sell or when to buy or sell them. The Information is provided “as is” and the user assumes the entire risk of any use it may make or permit to be made of the Information. No MSCI Party warrants or guarantees the originality, accuracy and/or completeness of the Information and each expressly disclaims all express or implied warranties. No MSCI Party shall have any liability for any errors or omissions in connection with any Information herein, or any liability for any direct, indirect, special, punitive, consequential or any other damages (including lost profits) even if notified of the possibility of such damages.
Related Post
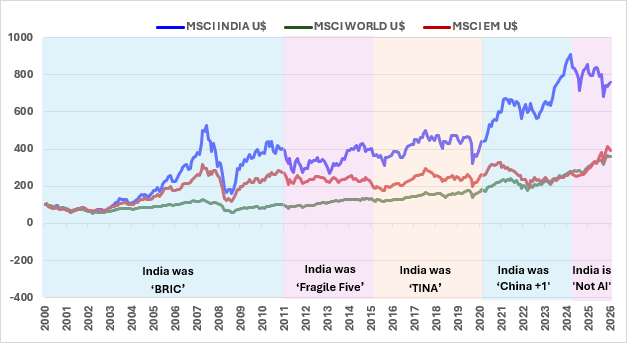
India Allocation as a Risk Diversifier
The India investing story is a simple story of consistent long-term real and nominal GDP growth, which is converted into revenues and profitability by firms, and which is reflected and rewarded by long-term returns in the stock market.
India: T I N A to A N T I
The Indian public equity markets peaked in September 2024. Since then, foreign investors have sold USD 51 billion till April 2026. The market value of foreign investor holding in Indian equities has fallen from USD 930 billion in September 2024 to USD 670 billion, a ~30% drop as at the end of March 2026.
Our Strategies
Explore how our two main strategies – Predictable India Equity and India Integrity Equity - with demonstrated success of our tried and tested research and investment processes can ensure your India equity allocation will have higher predictable outcomes and no surprises.
Q India Value Equity Strategy
20+ years of India Long-only, Liquid, High-Governance, Margin of safety = Predictability
Integrity screen since 1996, strategy Track record since 2000.
Q India Responsible Returns Strategy
Liquid, proprietary Integrity Scores, Financial Soundness
Integrity Screen since 1996, enhanced criterion since 2015, strategy Track Record since 2019; strategy AuM: $9.7 mn Mandate Capacity: $5 billion
Quantum Advisors pioneered a quantitative as well as qualitative analytical approach to equity investing in India, providing for the first time, consistently applied valuation metrics to evaluate investment opportunities in India’s emerging stock markets. Over the years, Quantum Advisors has continued and enhanced its tradition of extensive financial analysis and value investing, as it has evolved into an investment advisor and asset manager.
Our investment philosophy and strategy involves the use of intensive qualitative and quantitative fundamental analysis. We build and monitor our clients’ portfolios actively while at the same time avoiding excessive trading, and control risk by endeavoring to keep our clients’ portfolio adequately diversified, both in terms of the sectors included in those portfolios, as well as with respect to the level of concentration in any specific security.